Construction Spending Stabilizes, But Market Divide Persists
Recently, the US Census released the results of its monthly Value of Construction Put in Place Survey. The survey provides estimates of the total dollar value of construction work done in the U.S. This data includes design and construction spending for public and private projects.
U.S. construction spending showed a brief bright spot in August with a 0.9% month-over-month increase to $2.2 trillion. However, total spending is still down year over year at -1.7% (not adjusted for inflation). This now represents 13 consecutive months of year-over-year decline in total construction spending. Total Private construction is down -3.1% compared to Public spending which is up 2.5% year over year.
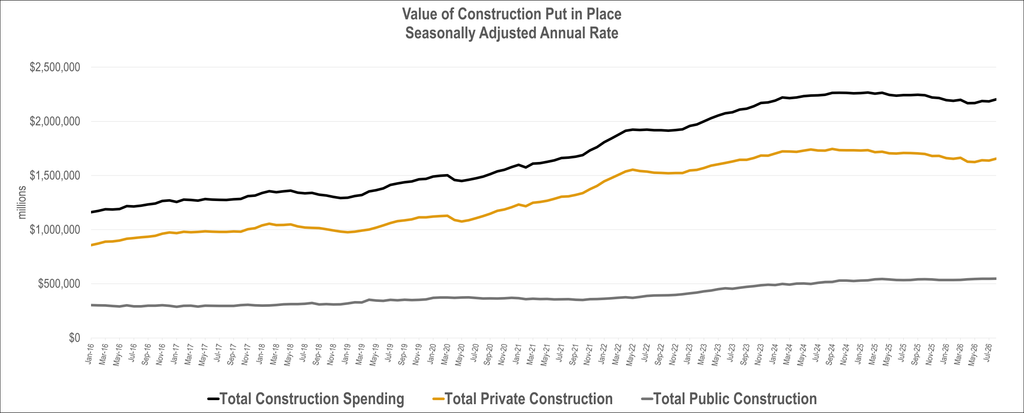
Source: US Census Value of Construction Put in Place Survey October 1, 2026 release
This recent improvement from the April 2026 lows mirrors the overall U.S. economy’s movement. The 2026 Q2 GDP was recently revised up from 1.5% to 2.1%.
Data shows that in aggregate, construction spending peaked in February 2025. Below the headline number, performance in individual markets has shown considerable variability. The Residential sector continues to struggle with higher borrowing costs and is down -4.8% year to date. The Nonresidential market has rebounded from declines at the start of the year to be up 0.5% year over year.
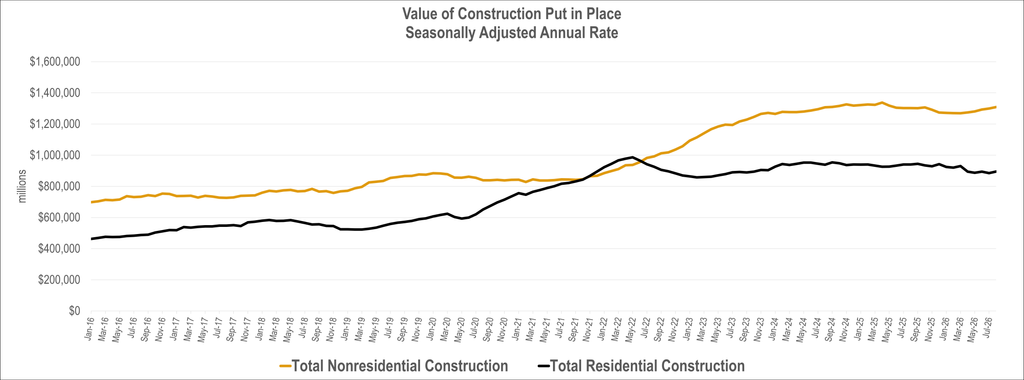
Source: US Census Value of Construction Put in Place Survey October 1, 2026 release
With respect to year-to-date growth in individual markets, 2026 is showing a continued divide with 10 markets experiencing growth and 7 experiencing a contraction.
The Power market continues to be the largest nonresidential market and has grown 4.6% year to date. Other top growth markets include the Office sector, up 11.2% year to date. This is due to the substantial growth in Data Centers, which are up 41.7% compared to last year for a total of $45.2b year to date. Religious, Conservation and development, and Amusement and recreation round out the 5 largest year-to-date increases.
Sectors that are in decline are lead by Manufacturing, which is down 21.8% year to date, though is the 2nd largest nonresidential market with total spending at $115.8b year to date. Sectors affected by higher costs of capital due to higher interest rates continue to contract, including Residential, Commercial and Lodging. Public Safety is also negative year to date.